A subcontractor's insurance lapsed while they were on our site. Are we liable?
It depends on your contract with the subcontractor, your own policies and the law where the work took place, so nobody can give a general answer. What you can do today is stop the subcontractor's work until current cover is confirmed, tell your insurance broker, and document every date. Then track each certificate of insurance with its expiry dates, an owner and an automatic request for the renewed certificate.
Last updated · ExpiryEdge editorial team
Quick answer
Whether you are liable depends on your contract with the subcontractor, your own insurance policies and the law where the work happened, so there is no safe general answer. Today: pause the subcontractor's site work until current proof of cover arrives, notify your insurance broker, and document dates and events. Then track every certificate of insurance with its expiry dates, a named owner and an automatic request for the renewed certificate.
What to do in the next 48 hours
1. Pause the exposure
Stop the subcontractor's work on your site until they provide current proof of cover, following whatever process your subcontract sets out. Tell them in writing why and what you need. If stopping work would itself create a safety risk, make the site safe first and then pause.
2. Find out whether the policy lapsed or only the certificate did
Often the policy renewed and you simply never received the new certificate. Ask the subcontractor for a current certificate of insurance, and ask their broker or agent directly to confirm the policy status and the dates of any gap. A certificate is evidence of cover on the day it was issued, not a guarantee that the policy is still in force.
3. Tell your broker and, if needed, counsel
Notify your own insurance broker of the gap, the dates, and any incident, injury or damage during that period. Your policies may have notice requirements. If anything went wrong on site while cover was missing, speak to a lawyer about your position under the subcontract and local law before making any admissions.
4. Document everything
Record the dates the subcontractor worked, who was on site, the certificates you held and when, every request you made, and every reply. Keep copies of the subcontract's insurance clauses. A clear timeline helps your broker, your insurer and your lawyer, whatever the outcome.
5. Check every other active subcontractor
If one certificate slipped, others may have too. List every subcontractor and vendor currently working for you, each policy type on their certificate, and its expiry date. Request updated certificates from anyone expired or expiring in the next 30 days before they are next on site.
Why it happened
Most lapses are found late because the certificate was checked once, at onboarding, and never again.
The certificate was collected once and filed
A COI is checked when the subcontractor is onboarded, then sits in a folder. Policies renew or lapse during the job, and nobody looks again until a claim or an audit.
One certificate, several expiry dates
General liability, workers' compensation, auto and umbrella cover can each expire on different dates. Tracking only the first date on the certificate misses the others.
The certificate on file did not match the policy
In a multiyear certificate audit described by David Dybdahl for IRMI (“Avoiding Common Insurance Certificate Errors”, 2015), 9 in 10 contractors had material defects between the COI on file and the policy actually in force, and 70% of the audited policies had material coverage gaps the certificate did not reveal.
Requests went by email and were ignored
Chasing renewed certificates by email depends on one coordinator remembering to follow up. When they are busy or leave, the requests stop.
How to stop it happening again
Track each coverage on the certificate separately
Record general liability, workers' compensation, auto, umbrella and any other required cover as separate items on the subcontractor's record, each with its own expiry date and the certificate attached. Reminders run at 90, 60, 30 and 7 days before each date, to your internal owner and to the subcontractor contact you add.
One item per coverage type
Certificate stored on the record
Reminders to your owner and the vendor contact
Request the renewed COI by upload link, no account needed
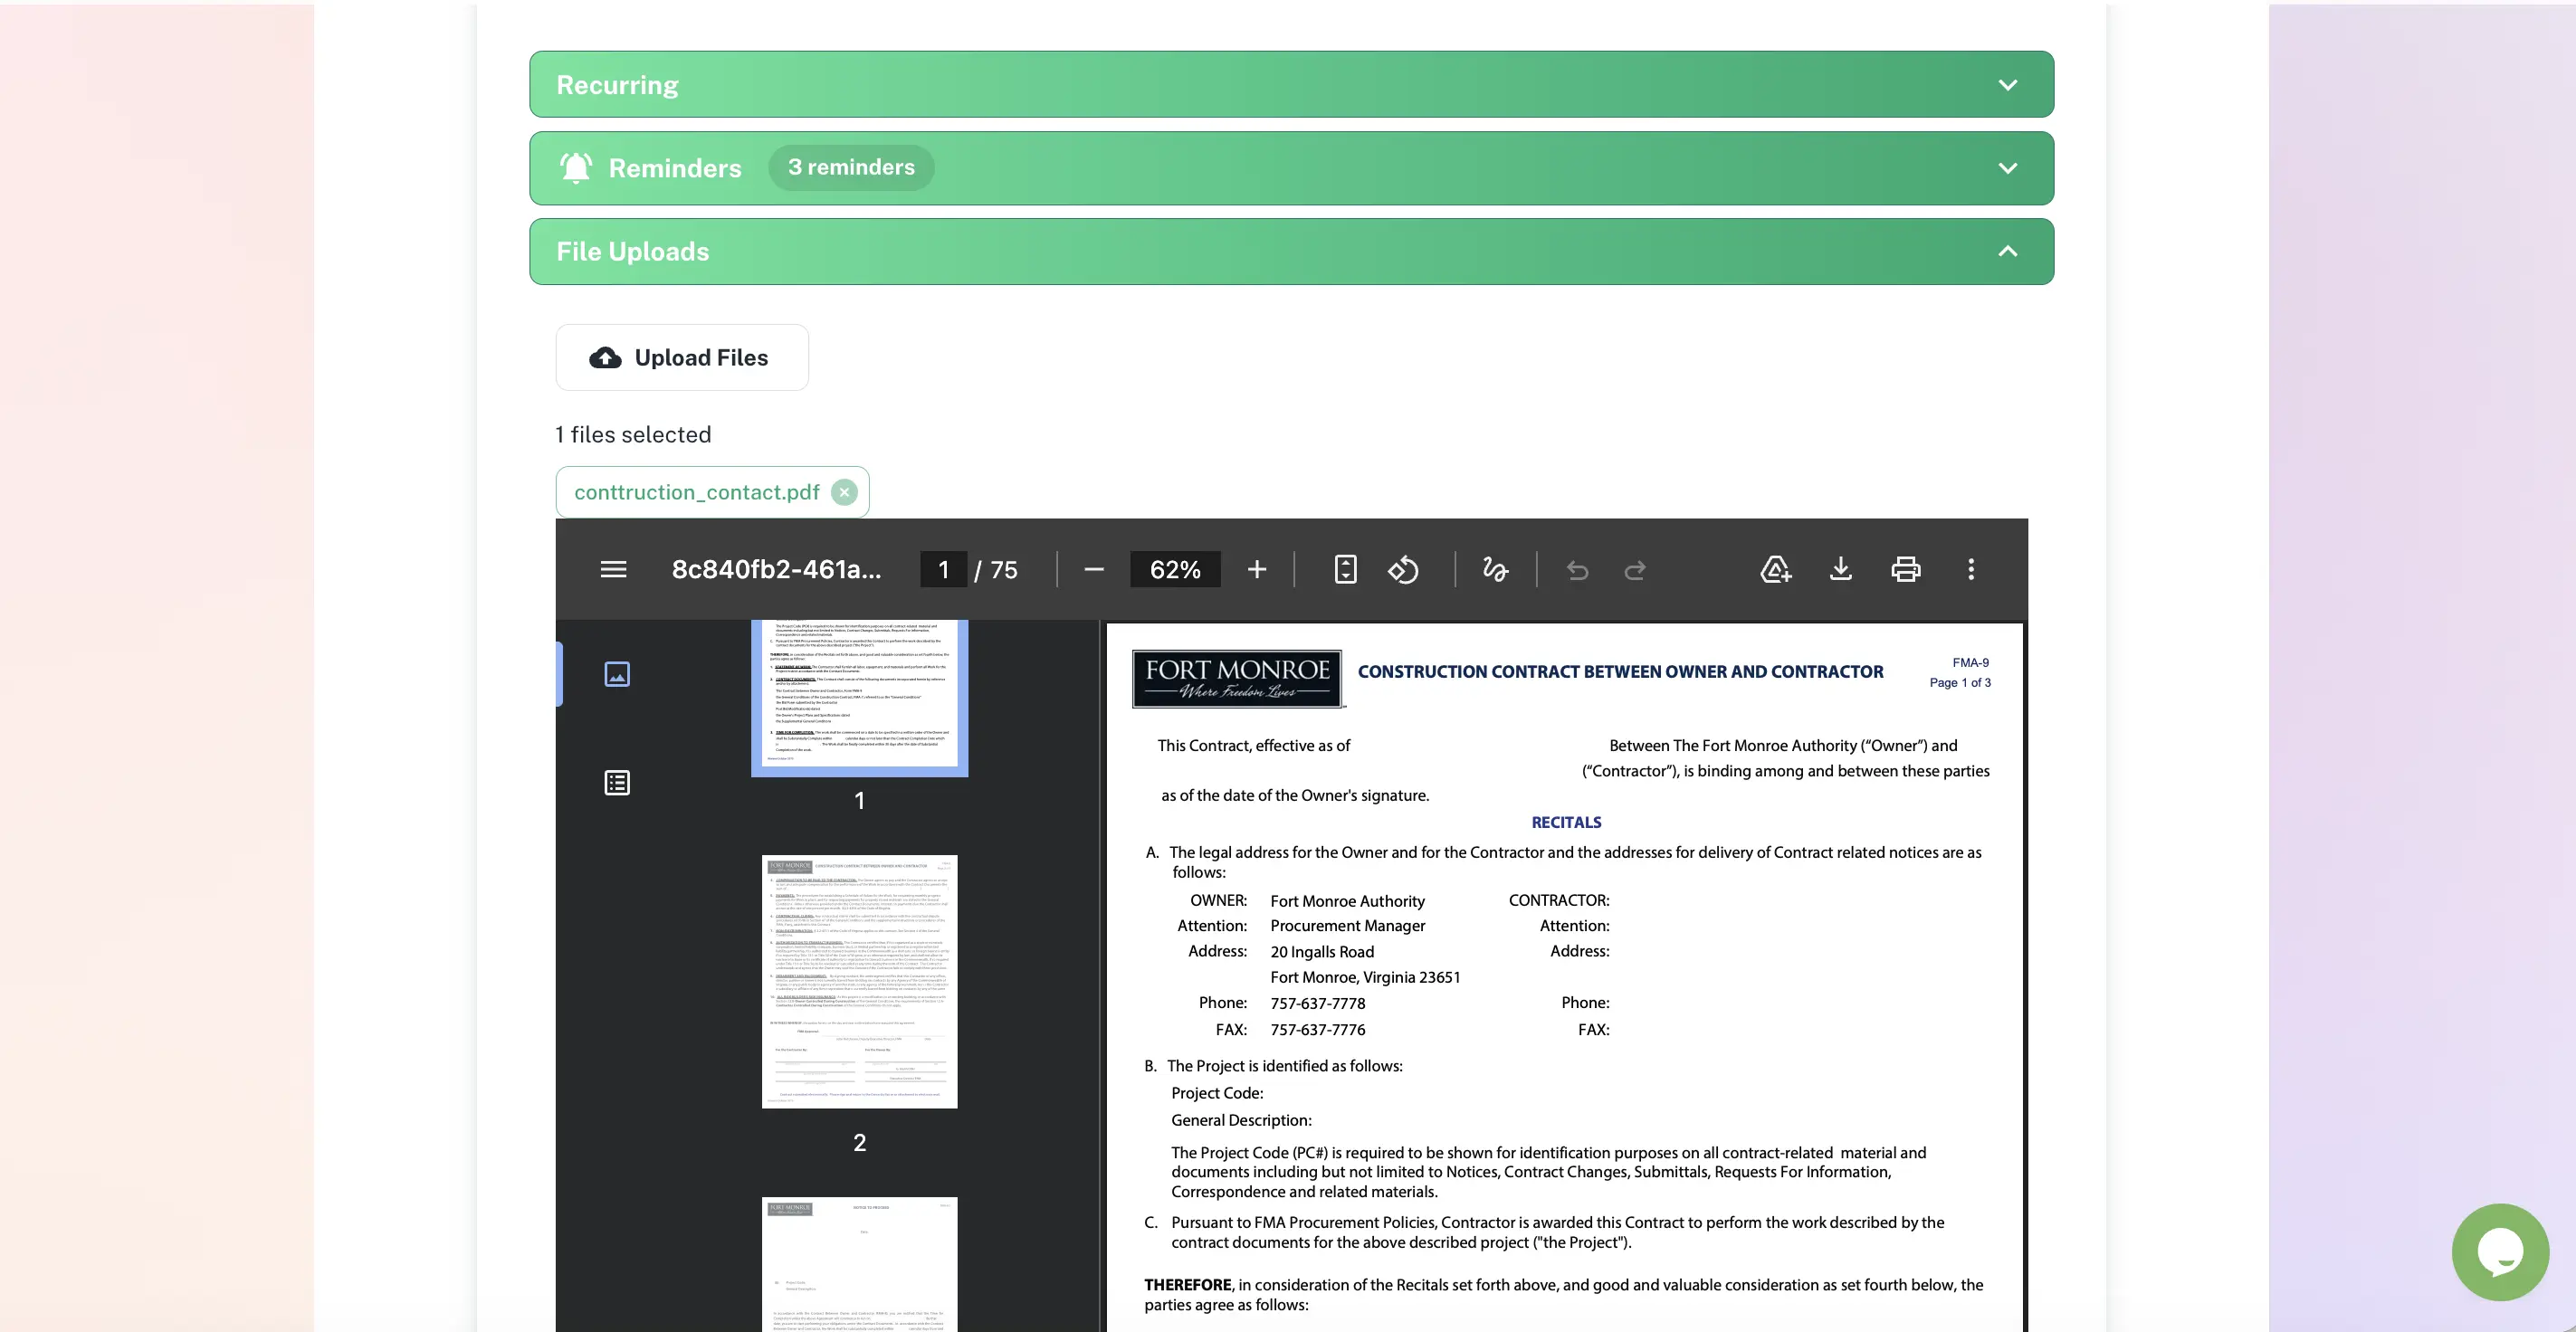
Before a certificate expires, send the subcontractor an ExpiryEdge upload link by email, SMS or WhatsApp. They upload the new certificate from any device without creating an account, and can e-sign any acknowledgement you require. You review the document; if nothing arrives, reminders continue and escalate to your senior owner.
Upload link with no login
E-signature for acknowledgements
Escalation if the certificate does not arrive
See who is cleared to work before they arrive
The dashboard shows each subcontractor as valid, expiring or expired, by project or site. Add a pre-start checklist so no one is booked on site until their certificates are current. Every request, upload and review is timestamped, and exports to CSV, PDF or XLSX for your insurer or an audit.
Status per subcontractor, per project
Pre-start checklist with owners
Timestamped audit trail and exports
There is no general answer. Liability depends on the subcontract's insurance and indemnity clauses, your own policies, what happened during the gap, and the law where the work took place. What you can control now: pause the subcontractor's work until current cover is confirmed, notify your insurance broker, document the dates and any incidents, and take legal advice if anything went wrong while cover was missing. Confirm with the subcontractor's broker whether the policy truly lapsed or only the certificate was out of date.
Record each vendor with every coverage type on their certificate as a separate item with its own expiry date, because general liability, workers' compensation and auto often expire on different days. Attach the certificate to the record and assign an internal owner. ExpiryEdge sends alerts at 90, 60, 30 and 7 days before each date by email, SMS, WhatsApp, Slack or Microsoft Teams, and escalates to a senior owner if a certificate expires without a replacement.
Set the request to go out before expiry, not after. A common pattern is a first request 30 days ahead, with follow-ups if nothing arrives. ExpiryEdge can send the vendor an upload link by email, SMS or WhatsApp; they upload the renewed certificate without creating an account, and it attaches to their record for you to review. If the certificate still has not arrived at expiry, the issue escalates to your internal owner.
Keep tenants and vendors on one register, grouped by property, with each required coverage, its expiry date and the certificate attached. Lease and service agreements usually set the required limits and named parties, so record those requirements next to each certificate. Reminders and upload requests go to the tenant or vendor before expiry, and the property manager sees which certificates are current across the portfolio and which are outstanding.
Make current certificates a condition of booking, not something checked afterwards. Before mobilisation, confirm each required coverage is in force for the dates of the job and meets the limits in your subcontract. Use a pre-start checklist with a named owner who signs off before the subcontractor is scheduled. In ExpiryEdge the dashboard shows each subcontractor as valid, expiring or expired by project, so the check takes a filter rather than a folder search.
Send a secure upload link instead of asking them to register on a portal. Contractors and small trades can then upload a photo or PDF from their phone in one step. ExpiryEdge document collection works this way: the contractor opens the link, uploads the certificate or licence, e-signs anything you need acknowledged, and the file attaches to their record with a timestamp, with no login required.
A certificate holder is the party the certificate of insurance is issued to; it shows that a policy exists but gives the holder no rights under that policy. An additional insured is added to the policy itself, usually by an endorsement, and may be covered under it for claims arising from the named insured's work, subject to the policy's terms. If your contract requires additional insured status, ask for the endorsement, not only the certificate. Your broker can confirm what a specific endorsement covers.
Know which subcontractors are covered before they are on site
Import your vendor list, track every coverage date, and request renewed certificates by upload link. Free 14-day trial, no credit card.